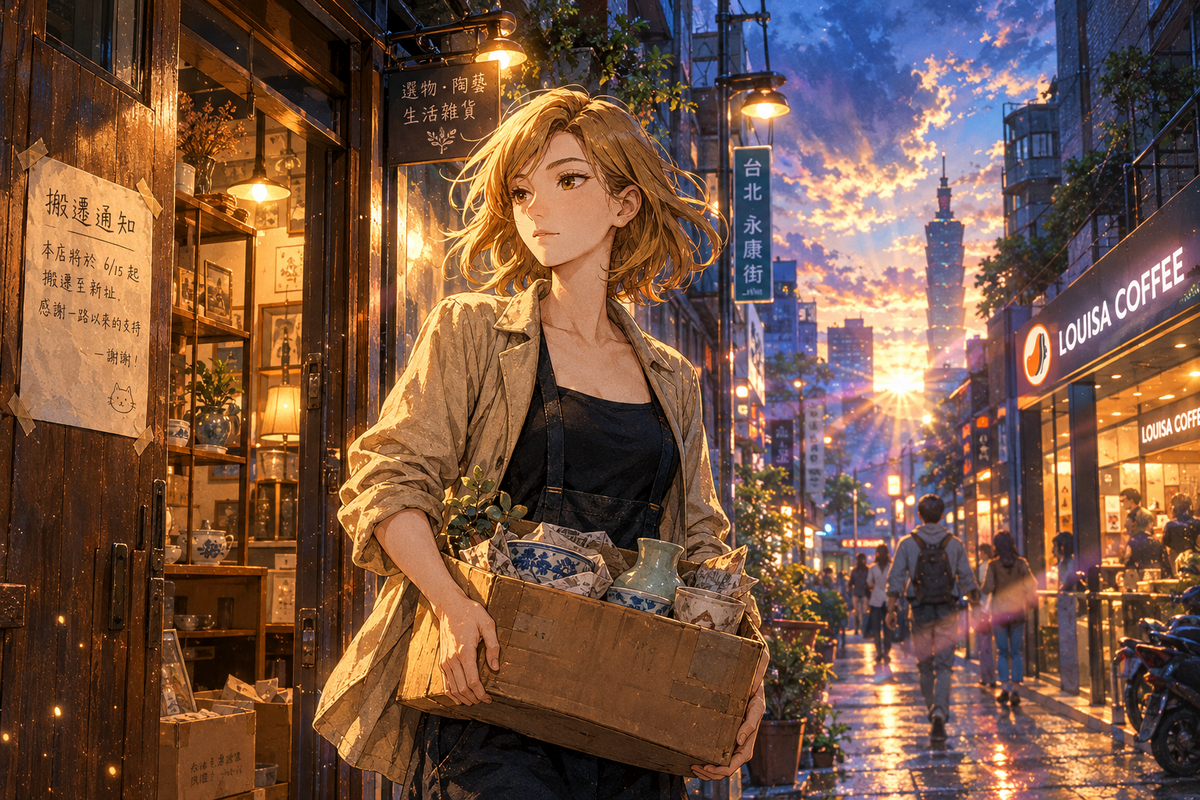
常去的那家店,某天門口貼了搬遷公告。赤峰街小店的故事,多半從這個畫面開始:木門還在,招牌換了人,隔壁的髮廊原址已經由 Levi’s 接手。
一杯水果塔的租金
聯合新聞網 2026 年 9 月中旬的報導,記下一家 2020 年進駐的水果塔甜點店。續約時租金被調到原來的三倍以上,店家遷往承德路二段。報導引述房仲的說法,每坪月租十年前約 3,000 至 4,000 元,如今約 8,000 元至 1 萬元。TVBS 引述的行情更高,每坪 1 萬 5,000 元至 2 萬元,兩組數字來自不同報導,不是同一份成交統計。
TVBS 受訪的專家還給了另一種讀法:部分店家五到八年前簽下較低租金的長約,到期一次調回市場水準,帳面上就成了兩三倍。這是受訪者的解讀,沒有逐筆租約可以驗證。三倍是真實的痛,也可能是多年低租金一次補齊的結果,兩件事可以同時成立。
另有一個容易被忽略的背景:赤峰街一帶多為住宅區,部分店家是依市府 2024 年放寬的納管措施附條件營業。熱鬧不等於合法使用狀態已經底定。
空了的店,與還沒空的街
報導足以確認店家替換,不足以宣告整條街沒落。Levi’s 願意接手空間,說明有人排隊要進來。戴德梁行 2026 年第二季的中山南京商圈沿街空置率是 4.70%,但那是沿街口徑,巷內赤峰街的空置、人流與營業額,目前沒有同口徑的時間序列可看。
街還在,換的是店的種類。獨立選物與甜點店離開,連鎖與國際品牌進來,街的面貌會變,客人回不回訪還得觀察。選物店消失的惋惜是真的,把個案寫成整條街的死亡證明則太快。
首爾、東京各自動了哪根槓桿
仕紳化的對策,各城市拉的是不同的桿。首爾 2015 年的綜合對策,明列由市府買入或租下不動產,再低價提供給小商家與文化藝術工作者。2018 年,全國性法律把租金調升上限從 9% 降到 5%,續約請求權的保障期間由 5 年延長至合計 10 年。「首爾型長期安心商鋪」用修繕補助換屋主的租期與調幅承諾,2018 年公告的補助最高 3,000 萬韓元。
東京走另一條路。《借地借家法》對拒絕續約設有正當事由要求,東京都 2026 年度的商店街創業方案包括三年店租補助,但公告裡沒有都政府直接購租店面。下北澤 BONUS TRACK 由小田急電鐵開發,規劃時先設定小型店鋪負擔得起的出店條件,再回頭設計建築。持有空間的是民間,不是市政府。
成效也有邊界。《京鄉新聞》2024 年的報導提到協約拘束力的問題,未納入保護範圍的聖水洞部分街區,仍承受快閃店與資金湧入的漲租壓力。制度壓得住一部分漲幅,壓不住全部市場。
買店面,還是修街道
台北有人提議向首爾、東京借鏡,由市府出面協助長租或購買需要保存的文化或店家。反方的提醒同樣有分量:熵診所的長文主張,一家店租不租得起,原則上由房東與承租人判斷與承擔;公共資源該花在人行環境、活動與散場動線,讓人走進百貨門外的街。保存案要成立,需要比「這家店值得喜歡」更充分的理由:保存的是名稱、技藝、公共使用,還是非得在這個地址才成立的關係。
巴黎真的買過店面,三項計畫合計 280 間,附帶可償還預付款與公共補助。巴塞隆納買空店再引進新用戶,後續營運進度一再延後。買店面是一種做法,花多少錢、保多久、帶動多少周邊使用,得逐項攤開算。
赤峰街小店搬去承德路二段之後,同一份水果塔還在賣。租約合不合理、街區要不要保存,尚待查證的資料,還躺在租約和空置率的欄位裡。
— 曾凡凡
When Chifeng Street’s Small Shops Left
The sign on the door announces a move. Stories about Chifeng Street’s small shops tend to begin there: the wooden door is still hanging, the nameplate belongs to someone else, and the former hair salon next door is now a Levi’s.
The rent behind a fruit tart
A late-2026 roundup of the Chifeng debate traces a mid-September United Daily News report on a dessert shop that moved in during 2020. At renewal its rent was raised to more than three times the old level, and the shop relocated to Section 2 of Chengde Road. The report quotes a real-estate agent: monthly rent per ping rose from roughly 3,000–4,000 NT dollars ten years ago to roughly 8,000–10,000. TVBS cited a far higher range of 15,000–20,000. Those are different reports, not one transaction dataset.
An expert interviewed by TVBS offered another reading: some shops signed long leases at low rents five to eight years ago, and when those leases expired the rent snapped back to market level in one jump. That is an interviewee’s interpretation, not something checked against individual leases. The tripling can be real pain and also a bill for years of below-market rent.
One more piece of background: much of the area is zoned residential, and some shops operate conditionally under measures the city loosened in 2024. A busy street does not prove every storefront is legally settled.
Empty shops, a street not yet empty
The reporting confirms shops being replaced. It does not confirm a street in decline. A Levi’s took over the salon’s space, which means someone wanted in. Cushman & Wakefield’s second-quarter 2026 street-front vacancy for the Zhongshan–Nanjing area was 4.70%, but that is a district measure; no same-basis series exists for the lanes of Chifeng Street itself.
In short, the street is still there and the kinds of shops are changing. Independent select shops and dessert counters leave, chains and international names arrive, and whether customers come back remains to be seen. Mourning a favorite shop is fair. Writing a death certificate for the whole street is premature.
Which lever Seoul and Tokyo pulled
Answers to gentrification pull different levers. Seoul’s 2015 package listed city purchase or leasing of property, then offering it cheaply to small businesses and artists. In 2018 national law cut the cap on rent increases from 9% to 5% and extended renewal-claim protection from 5 years to a combined 10. The “Seoul-style long-term safe shop” scheme traded repair subsidies, up to 30 million won in the 2018 notice, for landlords’ commitments on lease terms and increases.
Tokyo went another way. Japan’s Land and Building Lease Act requires justifiable grounds to refuse renewal, and the Tokyo Metropolitan Government’s 2026 shopping-street startup program includes a three-year rent subsidy, though its announcement contains no direct city purchase or leasing of shops. Shimokitazawa’s BONUS TRACK, developed by Odakyu Electric Railway, set affordable terms for small shops first and designed the buildings afterward. The holder of the space was a private company, not the city.
Results have limits. A 2024 Kyunghyang Shinmun report raised the question of how binding Seoul’s agreements are, and parts of Seongsu-dong outside the protected area still faced rent pressure from pop-ups and incoming capital. Rules can cap some of the rise but not all of the market.
Buy the storefront, or fix the street
In Taipei there is a proposal that the city help lease or buy shops and cultural venues worth preserving. The counterargument has weight too: the same long essay holds that whether a shop can afford its rent is, in principle, for landlord and tenant to judge, and that public money belongs in walkways, events and crowd-exit routes that pull people out past the department store doors. A preservation case needs a better reason than “this shop is lovable”: is it the name, the craft, the public use, or a relationship that only works at this address?
Paris has actually bought storefronts, 280 across three programs, with repayable advances and public subsidy attached. Barcelona bought empty shops and brought in new users, though its rollout slipped repeatedly. Buying is one tool; cost, duration and spillover each have to be itemized.
The fruit tart is still sold at the new address on Chengde Road. Whether the lease was fair and whether the street deserves protection are answers still sitting in lease files and vacancy tables.
— 曾凡凡
延伸閱讀
- 華山不只是酒廠:紅磚裡還藏著樟腦工場
- 大洲臥龍山莊以外:一張和紙,把台灣策展人帶進城下町
- 台鐵排骨便當開盒:先炸後滷的那一塊肉
- 新井耕吉郎紀念碑,立在一杯紅茶的源頭
- mysql2 讀 DATETIME 差 8 小時,一行 timezone: ‘Z’ 解決
https://justfly.idv.tw/s/czKzhgH